

On this page
Measure the work, not the signal.
See productive time and utilization by team, not just what looks active.

Key takeaways
- Branch network optimization helps banks decide where branches and ATMs are needed, while keeping essential services accessible to customers.
- As more banking moves online, branches handle fewer routine transactions but often more complex requests. Long leases and depreciation can delay the savings from a closure.
- A footprint decision combines customer usage and catchment, lease and depreciation exposure, access obligations, and site workload.
- Transaction averages don't tell you how much processing work a branch handles or whether its staff have capacity to take on more.
- Measuring workloads and throughput at each branch helps you make better use of your existing network and avoid shifting more work to locations that are already stretched.
Branch network optimization usually starts from averages: transaction counts, staffing levels, and opening hours. But two branches with identical transaction counts can carry very different amounts of work behind the counter. Averages don't reveal differences in actual workload.
Before you make changes to your branch network, you need to understand how work happens at each location and how those changes will affect capacity across the network.
What branch network optimization means
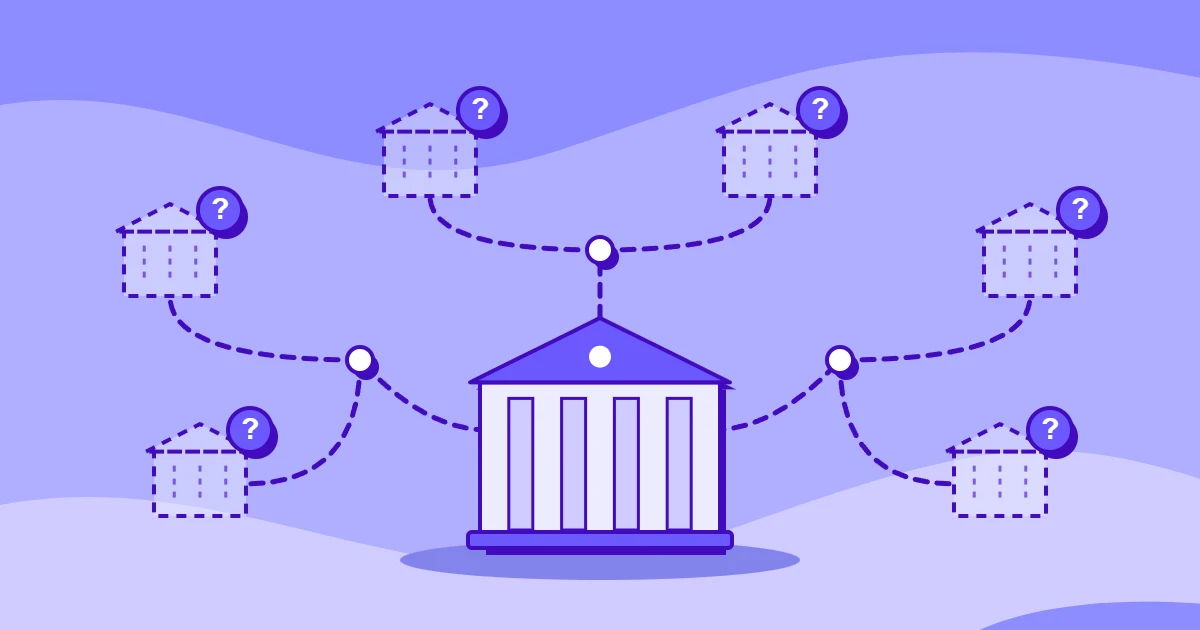
Branch network optimization is right-sizing a bank's physical footprint: closing, consolidating, or relocating branches and ATMs based on real customer usage as banking shifts to digital. The aim is to cut rent and depreciation without losing coverage customers still rely on.
But as routine banking moves online, the role of a branch changes, and so do the questions around branch network optimization.
For example, fewer customers may visit branches for everyday transactions, while those who do come in might need more involved support. That can change how much space a location needs without reducing its workload by the same amount.
The practical question in bank branch optimization is whether each location fits the role it now plays. A quieter site may still provide essential access to cash or handle processing work for other branches.
Keeping it in place or adapting how it's used may make sense, even when transaction figures suggest there's room to reduce the footprint. Closures also change how far customers travel to a branch. The Federal Reserve Bank of Richmond found that the US lost 5,413 branches between 2019 and 2023, while banking deserts grew by more than 6% nationwide.
You need to understand both sides of that usage: what customers need from the location and what work the bank carries out there. Both help establish which changes are practical.
Why rent and depreciation costs fall slowly
Rent and depreciation costs fall slowly because changing a branch network doesn't immediately remove its financial commitments. A bank may close a branch or reduce its physical footprint, but the costs associated with those properties can continue long after they're no longer in use.
Long-term leases are one reason. A bank may remain obligated to pay rent for years after closing a branch, unless it can exercise a break clause or negotiate an early exit with the landlord. Ending a lease early can also incur penalties, reducing the immediate savings from a closure.
Fit-out costs follow a different timeline. Investment in a branch's interior and equipment is generally depreciated over its useful life. Closing a branch may require the bank to write off remaining asset values or recognize impairment or disposal charges, bringing forward expenses before ongoing costs decline.
This means the physical infrastructure cost reduction a bank plans for can take years to materialize. Banks need to distinguish between costs they can eliminate immediately, obligations that will continue, and one-time expenses associated with closing or relocating a site.
What goes into a footprint decision
A footprint decision needs evidence of customer demand, the costs attached to each site, the access customers depend on, and the work the location handles. These inputs help you assess whether a proposed change is practical, when it can deliver savings, and how it would affect the wider network.
For branch network optimization, consider these four inputs:
- Customer transaction volumes and catchment: Establish how customers use each location, where demand is concentrated, and whether nearby branches could serve the same customer base. Use transaction data to assess demand and geospatial analysis to understand catchment areas, travel distances, and geographical coverage.
- Lease and depreciation profile: Look at when leases expire, what it would cost to exit them early, and how much value remains in each branch's fit-out and equipment. Closing a branch doesn't necessarily mean you stop paying for it. You need to account for ongoing commitments and one-time exit costs to understand when the savings would materialize.
- Regulatory and access obligations: Determine what requirements apply to a proposed closure or relocation, including any obligations to maintain access to banking services. In the UK, for example, the FCA's access to cash rules have required designated firms to assess local cash needs since September 2024. Some customers still rely on cash and face-to-face support, so even a branch with relatively few transactions could be important to the local community.
- Staff workload and throughput by site: Measure how much work gets done at each branch and whether other locations have the capacity to take it on. Transaction counts and staffing levels don't tell the whole story. They can miss back-office tasks, complex cases, and work handled for other branches, leaving you with an incomplete picture of the capacity you'd need elsewhere.
Where averages hide the answer
When reviewing branch footprints, banks typically use average transaction counts to compare how heavily branches are used. But averages don't show how much work each transaction creates or how demand varies through the week. Those differences are critical when judging whether a location has spare capacity or could absorb work from elsewhere.
Suppose two branches report identical monthly transaction counts. At one, most requests are straightforward and follow a standard process. At the other, staff deal with more complex cases that need extra review, or spend time following up on missing documentation.
All that additional work takes time, but doesn't necessarily show up in transaction totals. The second branch might also handle back-office tasks for neighboring locations, adding to its workload without increasing its transaction count.
In this example, the second branch is supporting more work than its customer-facing figures suggest. Common branch office issues can help explain why apparently similar locations have different capacity needs.
Workloads also vary throughout the week and month. A branch might appear to have spare capacity based on its weekly average, even though staff struggle to keep up on busy days.
The same applies over longer periods. A relatively quiet week might be followed by a surge in processing work at month-end. Having spare capacity on one day doesn't necessarily help when work piles up on another.
These differences affect how much work a location could take on if its role changed. Before treating two sites as interchangeable, you need evidence of the work each handles and how demand varies across days and weeks. Average transaction counts alone won't give you those answers.
What to measure before deciding
Before making changes to your branch network, you need to understand how much work gets done at each location, how much capacity it uses, and when demand is highest. That means looking beyond customer transaction counts to measure the processing work happening behind the scenes.
Focus on three areas:
- Throughput by site and week: Measure how much work each branch completes, then look at how that changes from day to day and week to week. Make sure you're comparing similar types of work and accounting for busy periods. Otherwise, a branch that looks underused on average might be struggling to keep up when demand peaks.
- Time spent on routine work versus exceptions: Look at how much time goes into straightforward requests compared with cases that need corrections, extra checks, or additional review. Use case records from your operational systems to understand the mix of work. This helps explain why two branches can complete similar numbers of requests but need very different amounts of staff time.
- Back-office work handled locally: Find out what processing tasks each branch performs beyond serving its own customers, including work it takes on for other locations. Measure how much time those tasks require. If you plan to move that work elsewhere, you'll need to know whether the receiving branch has enough capacity to handle it alongside its existing workload.
Together, these make workforce measurement in financial services more useful for branch network decisions. You can see where capacity is available, whether another site could absorb additional work, and how changes might affect day-to-day operations. That gives you a stronger basis for weighing operational capacity against property costs and customer access.
Find the capacity your network already has
A footprint review usually asks which branches to cut. Workload data answers a second question: how much more work your existing network can carry before you pay for more space or more staff.
Seen this way, a quiet branch can take on a new role. It may have room to absorb back-office work from a stretched neighbor, or to handle the complex cases that digital channels send back to the counter.
Insightful's People Intelligence shows how people work and suggests opportunities to improve output. Its Workload Balance opportunity looks at what people at each branch spend time on and suggests how to reorganize work across sites. You can then see which branches have room and which are at their limit.
With teams set up by branch, People Intelligence compares each site with branches that do similar work. That analysis builds on the capacity data in Workforce Analytics.
Neither product measures customer footfall or catchment areas. Weigh their findings alongside catchment analysis, lease commitments, and access obligations before you decide which changes to make.
Request a Work Audit to see where capacity sits across your branches in 14 days, on your own data.
Frequently asked questions
What is branch network optimization?
Branch network optimization means adjusting the size and location of a bank's physical network to better match how customers use its services. This can involve closing, combining, or relocating branches and ATMs as more banking moves online. The goal is to reduce property costs without making it harder for customers to access the services they still need in person.
How do banks decide which branches to close?
When deciding which branches to close, banks weigh customer usage and catchment, lease commitments, remaining asset costs, access obligations, and site workload. They also assess whether alternatives can serve affected customers and support any transferred work. A low transaction count alone doesn't establish that a change is practical or financially beneficial.
What costs does closing a branch actually remove?
Closing a branch can save money on utilities, cleaning, security, and maintenance. Rent costs may also fall, but that depends on when the lease ends. The bank may also face charges for remaining fit-out and equipment costs, so closing a branch doesn't mean its entire operating budget disappears overnight.
How has digital banking changed branch networks?
Digital banking moves some routine transactions away from branches, changing both visit volumes and the support customers need in person. However, fewer visits don't necessarily mean less processing work or less need for local banking services. As a result, banks are reassessing where branches are needed, how large they should be, and what services they should offer.